


The latest episode of The Albatross is about IRS's new Revenue Ruling on §351 transfers to ETFs.
|
Coming soon... The tax-aware adviser community.
The community is for Tax Alpha Insider paid members that advise households: planners, advisers, CPAs, attorneys, family office professionals, etc.
For the last few years, the ETF industry has used §351 of the Internal Revenue Code to let investors seed new exchange traded funds with appreciated securities, mostly stocks and other ETFs, without recognizing the gains.
This has become a thing.
By my estimate something like 116 ETFs have launched using §351 in some form, with about $21 billion in assets.
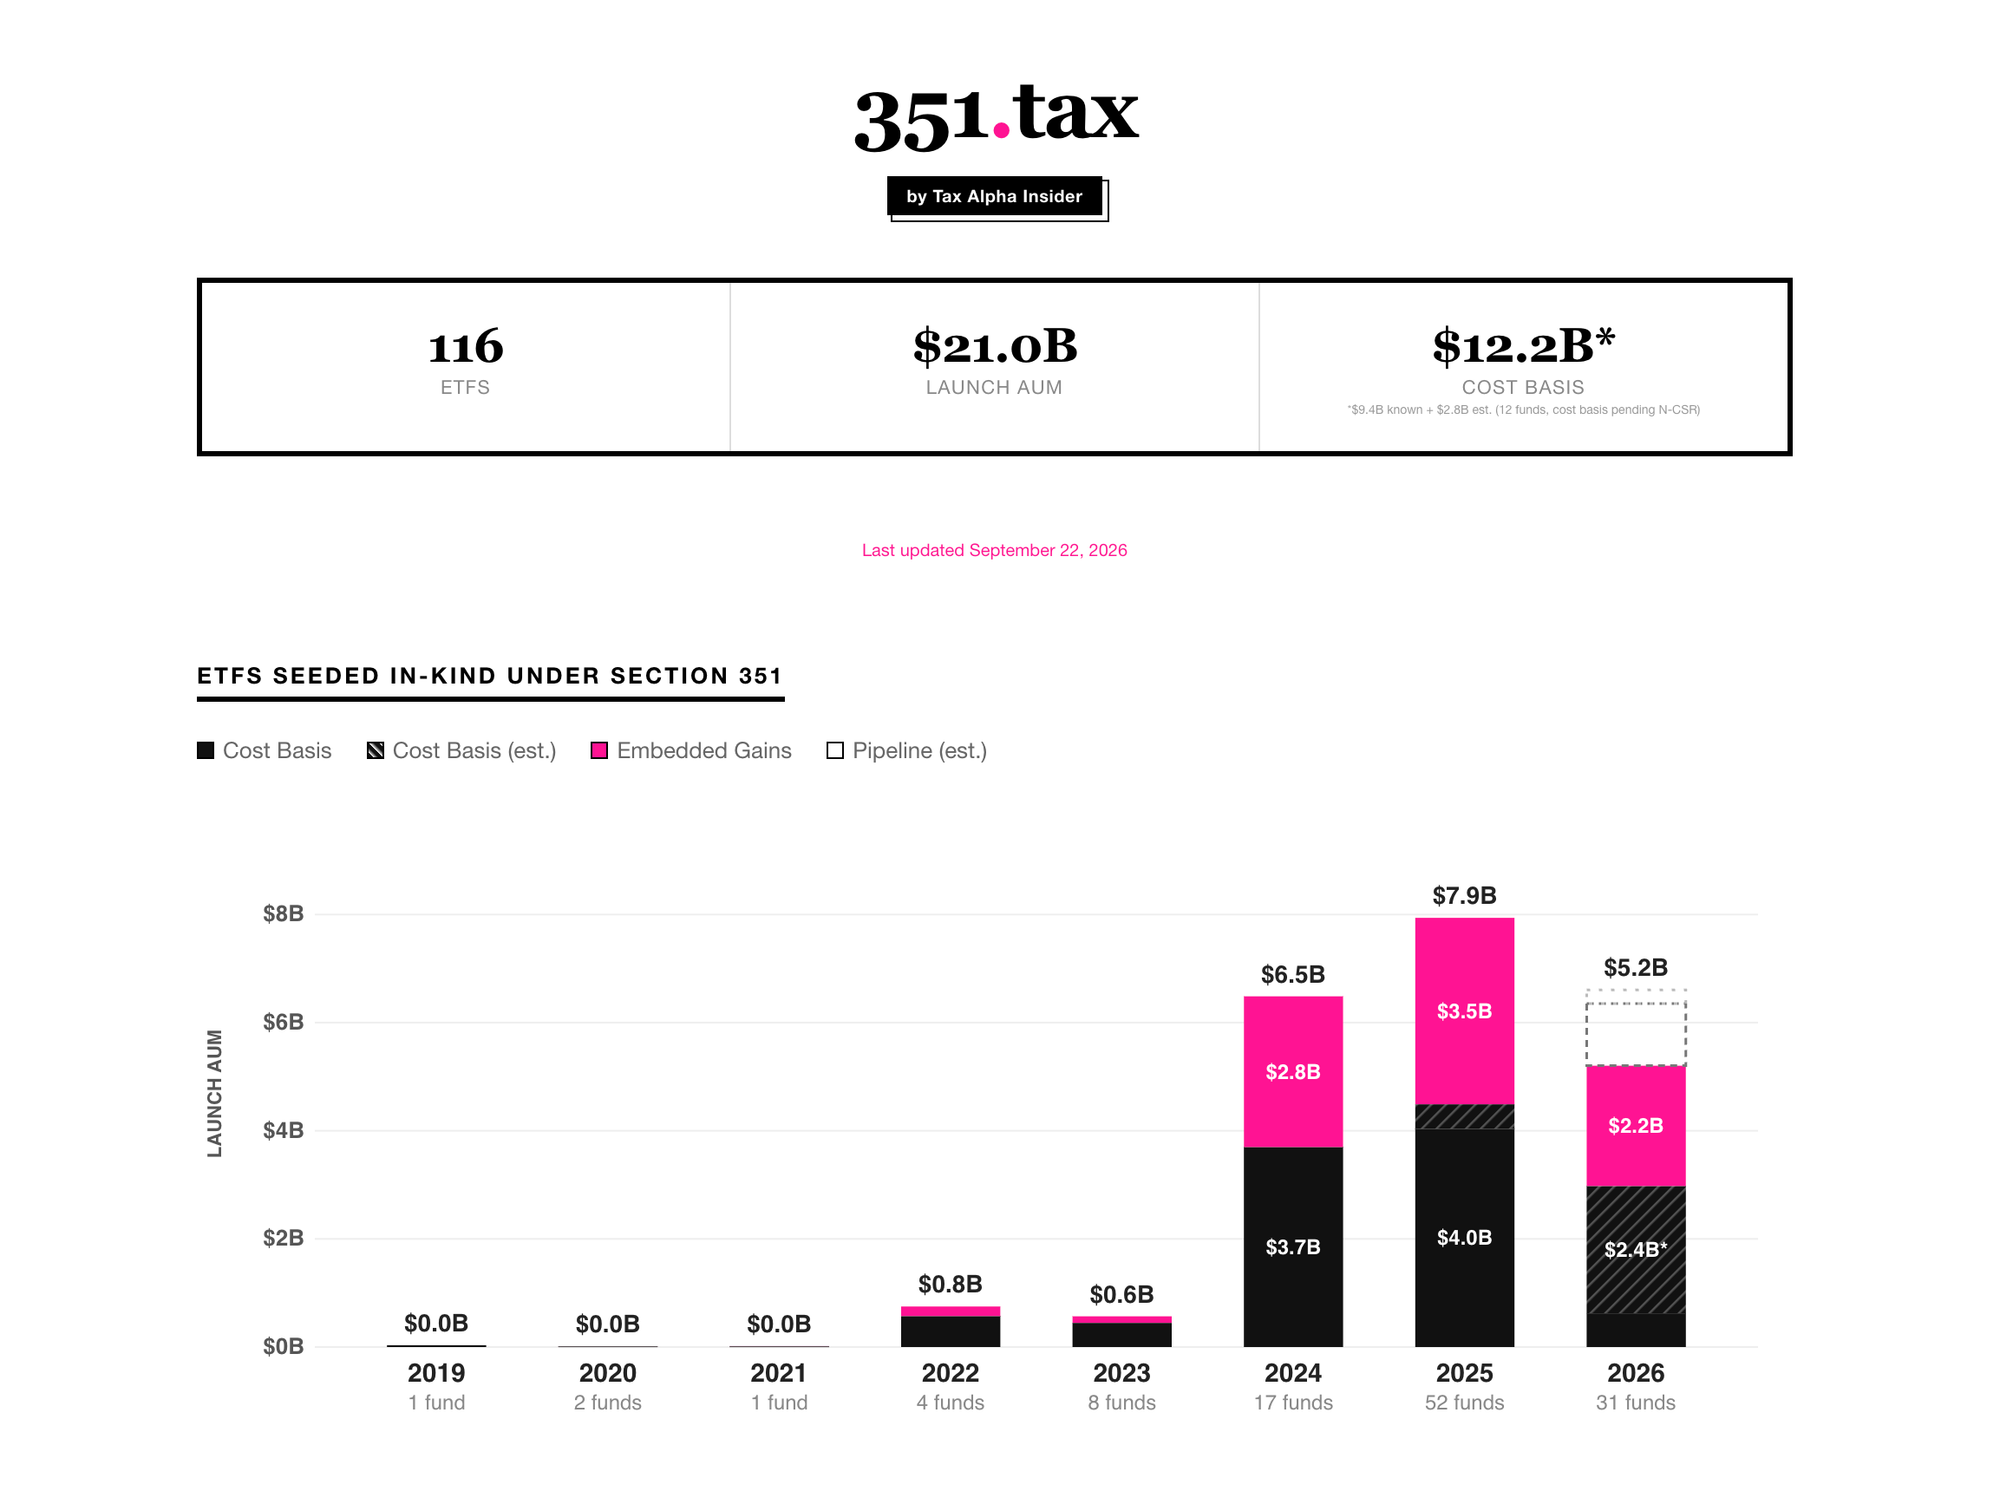
On Monday, 9/28/2026, Treasury and the IRS threw cold water on the most egregious uses of §351 with a new revenue ruling.
While some folks are nervous about this, others are exuberant.
In their minds, finally, Treasury has provided a little clarity around what routine usage of §351 looks like.
The key is knowing the difference.